How to prepare for an Agreement in Principle
Before requesting a mortgage Agreement in Principle, organise the information you will enter and the questions you need answered. Then keep a short record of the result and its limits.
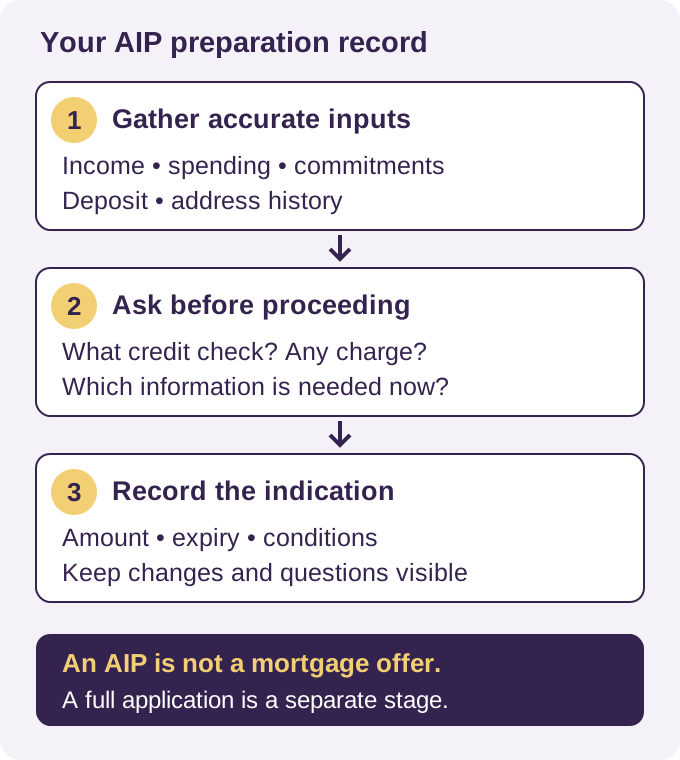
Start by checking what you are requesting
An Agreement in Principle (AIP), also called a Mortgage in Principle or Decision in Principle, is an indication of possible borrowing. It is not a formal mortgage offer. MoneyHelper explains the distinction.
Ask who will issue the result and what checks it includes. Keep a calculator illustration separate: using our borrowing calculator does not obtain an AIP.
What information should I have ready?
Prepare accurate figures for each applicant. Halifax’s AIP guidance asks for income, outgoings, existing credit agreements and address history. Check the provider’s own requirements before starting.
- Personal details: have your address history and dates ready so you can answer the requested questions consistently.
- Income: note the amount and whether it is annual or monthly, before or after tax. Keep variable earnings separate so you can ask how to enter them.
- Spending and commitments: use your records to list regular costs and existing credit payments.
- Deposit: note the amount available and its source. Keep purchase costs separate when planning your budget.
This is a preparation note, not a universal document checklist. MoneyHelper’s application guide explains that requested documents vary and that evidence will be needed for the mortgage application. Ask which documents are needed now and which come later.
If an income question is unclear, write it down instead of guessing. Our self-employed guidance covers the wider income-evidence conversation.
Will the credit check affect my credit score?
Ask before you proceed. MoneyHelper explains that providers can use different credit checks and that repeated hard searches in a short period can affect your credit rating. Halifax describes a soft check for its own AIP; do not assume another provider follows the same process.
- Will this request involve a soft or hard credit search?
- Would updating or renewing it involve another search?
- Is there any charge for the service at this stage?
Record the answers with the provider’s name and the date. For a separate accuracy check, use our guide to checking your credit reports.
What should I record when I receive the result?
Keep the indication and its conditions together. Use these headings in your own notes:
- Result: issuer, date and the amount indicated.
- Basis: the deposit, income and other details you entered.
- Validity: the expiry date stated, or a question to ask if none is clear.
- Conditions: anything still to verify and the next step requested.
- Changes: anything that has changed since the request, with a reminder to ask whether the indication needs updating.
There is no single expiry date to assume for every AIP. Check the actual result and ask how renewal works. Halifax also explains that changed circumstances or lender criteria can lead to a different decision at full application.
Example: you receive an indication, then realise the deposit entered included money set aside for legal costs. Note the corrected figure and ask the provider what needs updating before relying on the earlier amount. Do not silently carry the old figure into a later application.
Does an AIP mean I will get the mortgage?
No. A full application and assessment of the property still follow. An AIP cannot guarantee acceptance, and the figure is not a substitute for checking what repayments fit your household budget.
Keep unanswered questions with your record and take them to your mortgage conversation. For the wider process, return to our first-time buyer guide or buying-a-home guide.
To discuss your next step, use the existing first-time buyer callback form. It explains how your enquiry is referred to MGI Network Ltd, the advice partner; requesting a callback does not obtain an AIP. Keep financial documents and account details out of the optional notes.
Sources
- MoneyHelper: what happens when I get a mortgage in principle? — terminology, checks and limits.
- Halifax: what is a mortgage Agreement in Principle? — preparation information and its own process.
- MoneyHelper: the mortgage application process — later application evidence and assessment.
Information checked 19 October 2026. General information, not a personal mortgage recommendation.
Discuss your circumstances